Many seniors worry that a chronic diagnosis will block every life insurance option, but the practical truth is clear: most people with diabetes, heart disease, or COPD can still Get Approved for Final Expense Insurance because carriers use simplified-issue and guaranteed-issue underwriting instead of full medical exams. This guide, updated for 2026, explains the differences, the common underwriting triggers, and the step-by-step actions that increase your approval odds so you can apply with confidence rather than guesswork.
Below I summarize the seven practical steps I take clients through, then expand each one so you can follow the exact sequence an experienced agent uses.
Follow these seven steps to improve your odds:
- Assess your health tier and record your medical history.
- Answer application health questions honestly.
- Decide simplified-issue or guaranteed-issue based on your answers.
- Learn how graded benefits and waiting periods work.
- Gather medication lists and essential documents.
- Compare carrier approval rules and rates.
- Apply through an independent agent who shops many companies.
On this page · Updated October 2026 · 10 min read
- How do I assess my health tier before applying?
- How should I answer health questions on the application?
- Should I choose simplified-issue or guaranteed-issue coverage?
- What are graded benefits and waiting periods?
- What documents should I have ready before I apply?
- How do carriers differ on approval criteria and rates?
- How do I apply and avoid common mistakes?
- Key Takeaways
- Frequently Asked Questions
- Sources
- About the Author
How do I assess my health tier before applying?
Most carriers place applicants into a risk tier based on diagnoses, recent hospitalizations, and prescribed treatments; knowing where you likely fall helps you pick the right policy type and carrier. Start by taking inventory of chronic diagnoses, recent ER visits or surgeries, current medications, and whether you use oxygen or other assistive devices, these factors shape underwriting more than age alone. This quick self-audit keeps your expectations realistic and helps your agent target the companies most likely to approve you.
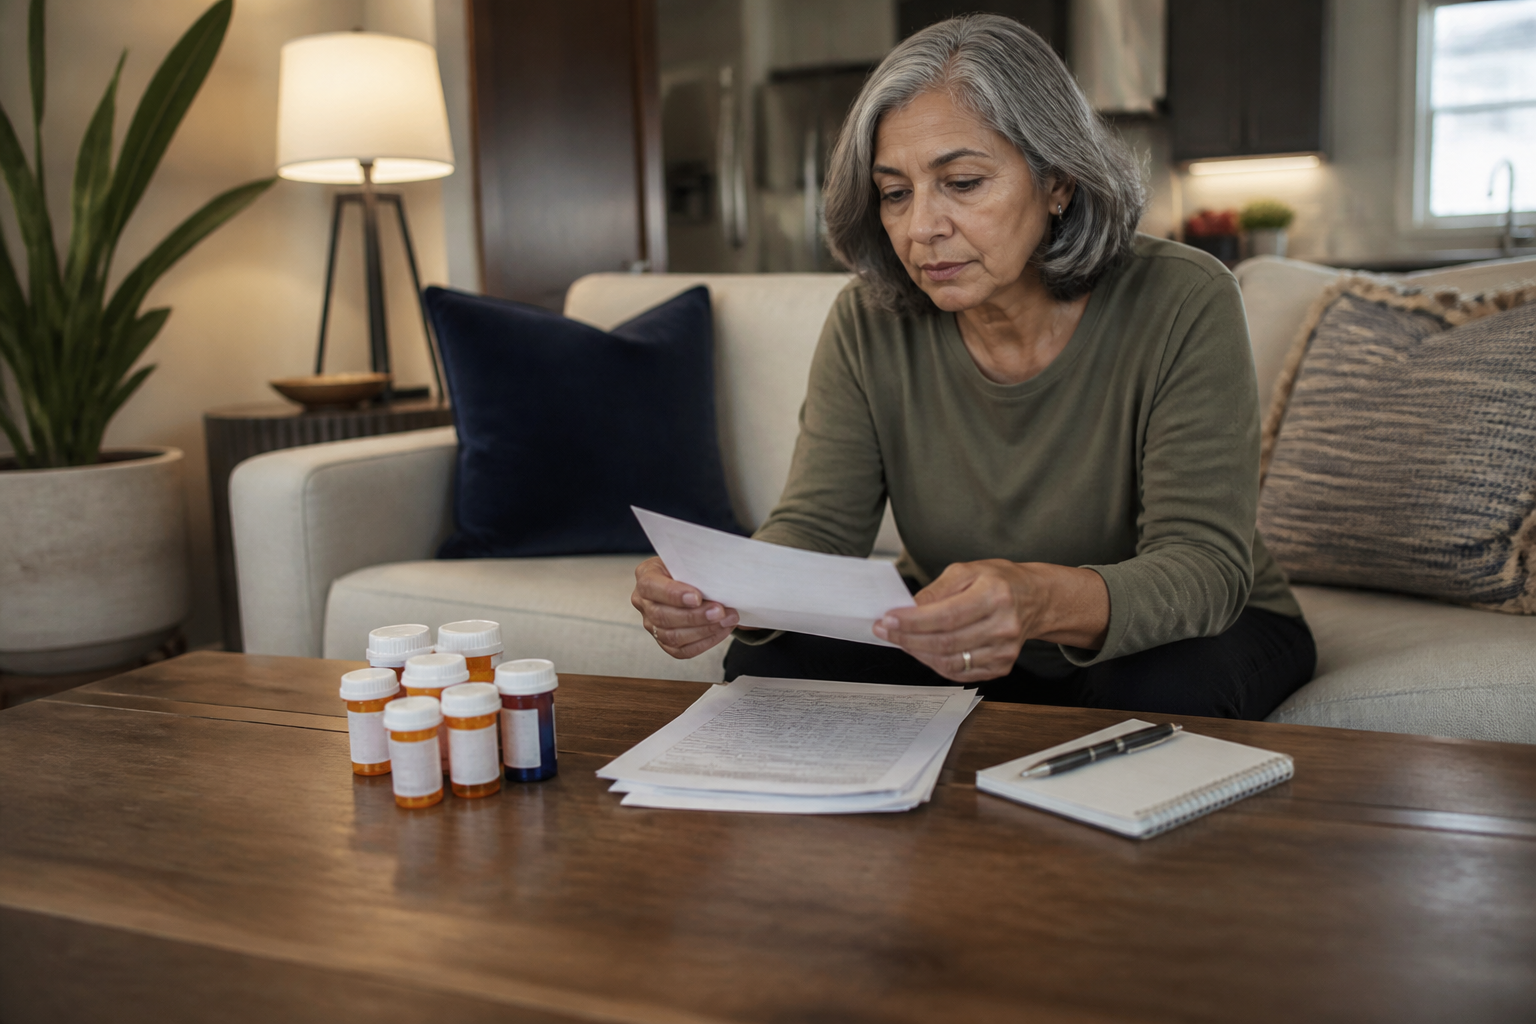
A practical self-assessment avoids surprises later in the process. Instead of guessing dates, pull doctor notes or pharmacy lists where possible; carriers commonly cross-check prescriptions, so an accurate medication list prevents mismatches. With this baseline, you will be ready to answer the application questions in Step 2 and understand whether simplified-issue or guaranteed-issue products are the right fit.
How should I answer health questions on the application?
Give complete, truthful answers, honesty protects your coverage and your family’s future. Simplified-issue applications use targeted yes/no health questions about recent cancers, cardiac events, oxygen use, and nursing home residence; accurate answers let carriers place you in the correct product, while omissions can create grounds to deny a claim during contestability. If a health question triggers a decline for simplified underwriting, it usually only means you should apply for a guaranteed-issue plan instead.
From experience, applicants who prepare by reviewing their records and medications tend to complete the phone interview faster and with fewer clarifying calls. If you are ever unsure about a question, note it and ask your agent to confirm how the carrier defines the timeframe or condition, it is better to clarify than to guess.
Should I choose simplified-issue or guaranteed-issue coverage?
In most cases, choose simplified-issue if you can honestly pass the carrier’s health questions, because it usually gives lower premiums and immediate full coverage; choose guaranteed-issue if your answers trigger a decline or if you prefer an acceptance with no health questions. The difference affects price, coverage timing, and the underwriting path, so match your health profile to the product rather than picking the cheapest ad you find.
To weigh the trade-offs quickly: simplified-issue commonly offers better rates and higher face amounts but requires passing health checks; guaranteed-issue accepts nearly everyone and may have a graded waiting period and higher premiums. Use this pros and cons block to see the comparison at a glance.
Pros
- Simplified issue often has lower premiums and immediate full benefits
- guaranteed issue offers acceptance with no health questions
Cons
- Simplified issue can require unanswered health questions to be “no”
- guaranteed issue usually has a waiting period and higher cost
After you decide which route fits your health profile, learn how waiting periods work so you understand what beneficiaries will receive if the insured dies during the early months of the policy.
What are graded benefits and waiting periods?
A graded benefit policy reduces or limits natural-death payouts during an initial waiting period, then pays the full death benefit after that period ends; this structure lets companies accept higher-risk applicants while reducing early claim exposure. During the graded window many guaranteed-issue policies refund premiums plus interest for natural-death claims, while accidental deaths are typically paid in full from day one.
Because the exact waiting period, refund amount, and interest rate vary by carrier and state regulation, read the policy’s fine print carefully. Ask your agent to show you the specific waiting-period language for any quote so you can compare how soon a family would receive the full benefit versus a refund of premiums.
What documents should I have ready before I apply?
Having a concise, accurate packet ready speeds approval and reduces back-and-forth: a current medication list, doctor contact numbers, and dates for recent hospital stays or procedures are the most useful items. Carriers often check prescription databases during underwriting, so your application answers should match pharmacy records to avoid verification delays or requests for clarification.
Gather these essentials before the phone interview: a medication list with dosages as shown on labels, names and phone numbers for your primary and specialist physicians, dates of any recent hospitalizations or surgeries, a timeline for major diagnoses, and a government-issued ID. If you want a quick estimate of how much coverage to target for burial and funeral costs, use an online tool like our funeral expense calculator to turn those projected costs into a recommended face amount; that makes it easier to select the right policy size when you apply. 1
How do carriers differ on approval criteria and rates?
Carriers vary widely on which conditions they consider acceptable for simplified underwriting, so shopping multiple companies is the most effective way to find approval at the best price. Some insurers are more forgiving with controlled diabetes on oral medication; others accept certain cardiac histories if the event was several years ago and follow-up care is stable. A profile that is declined by one carrier may be approved at a different company with the same face amount and a better premium.
A few underwriting patterns to watch: insulin use and complications often shift applicants toward guaranteed-issue; recent cardiac events typically require a waiting period; and daily oxygen use frequently routes an applicant to guaranteed-issue products. For cancer histories, carriers look at treatment completion and remission timelines, and the American Cancer Society’s survivorship guidance mirrors how underwriters evaluate long-term remission vs recent treatment. 2 An independent agent who understands these nuances will compare waiting periods, maximum face amounts, and contestability terms across carriers to find the best match for your situation.
How do I apply and avoid common mistakes?
Apply through an independent, licensed agent so one conversation can access multiple carriers, this approach reduces the chance of unnecessary declines and speeds approval. The application itself is typically a short written form plus a recorded phone interview that repeats the same health questions, and an experienced agent will prepare you for that interview so answers are consistent.
Common application pitfalls to avoid include leaving a prescription off the form, using a name that does not match your ID, guessing diagnosis or procedure dates, choosing guaranteed-issue when simplified-issue is actually available, and picking a face amount without estimating realistic funeral costs. Watching for these errors keeps your application clean and preserves your chances for immediate full coverage when possible. When you are ready, an agent can illustrate carrier-specific rules and place the application where your health profile has the best approval odds.
Key Takeaways
- Most seniors with chronic conditions can still Get Approved for Final Expense Insurance because carriers use simplified-issue and guaranteed-issue underwriting instead of medical exams.
- Simplified-issue gives lower premiums and often immediate full benefits if you pass the health questions; guaranteed-issue offers acceptance with higher cost and an initial waiting period.
- Read waiting-period language carefully: during the graded window many policies refund premiums plus interest for natural deaths, while accidental deaths are usually covered immediately.
- Prepare a medication list, doctor contacts, and basic medical dates before applying, and work with an independent agent to compare multiple carriers.
Frequently Asked Questions
Can you get burial insurance with pre-existing conditions?
Yes. Burial insurance is designed for applicants with pre-existing conditions by using simplified-issue or guaranteed-issue underwriting, not a medical exam. Some conditions may steer you to a graded policy with a waiting period rather than immediate full coverage.
How long is the waiting period on guaranteed-issue final expense insurance?
Waiting periods vary by company and state but many guaranteed-issue products use an initial graded window for natural deaths. If a natural-death claim occurs during that window, the policy often refunds premiums plus interest; accidental deaths are usually covered in full immediately.
Will I need a medical exam to be approved?
No. Final expense policies do not require a medical exam. Simplified-issue applications use a short set of health questions, while guaranteed-issue applications ask none, though carriers typically verify prescriptions against pharmacy records.
What happens if I answer a health question incorrectly?
Providing incorrect answers can give the insurer grounds to deny a claim during the contestability period, commonly the first two years of a policy. That is why complete, accurate answers and matching pharmacy records matter; if a question would cause a decline, an agent can recommend a guaranteed-issue option instead.
Does V Vega Insurance help seniors outside Arizona?
Yes. V Vega Insurance is licensed in many states, including California, Florida, Texas, North Carolina, Ohio, and more, allowing us to compare carriers and place policies based on each state’s rules and the applicant’s health profile.
Helpful next steps include Contact V Vega Insurance, Get Approved for Final Expense Insurance, and funeral expense calculator.
Sources
- National Funeral Directors Association. Funeral costs and planning resources. n.d. https://nfda.org
- American Cancer Society. Survivorship resources and information. n.d. https://www.cancer.org
- Centers for Disease Control and Prevention. About Chronic Diseases. n.d. https://www.cdc.gov/chronic-disease/about/index.html
About the Author
This article is for general educational purposes and is not professional advice. Consult a licensed professional about your specific situation.
Get a Free Quote: Call 602-935-5017
If a health condition makes you worry you cannot qualify, V Vega Insurance will evaluate your exact medical history, compare multiple carriers, and identify whether a simplified-issue or guaranteed-issue final expense policy is the best path. We place policies across the states we serve so you avoid unnecessary declines and get a quote tailored to your health profile and budget.